FASB Proposes Recapture in Mortgage Servicing Valuations
Published Nov 6, 2026 · Insights Brief
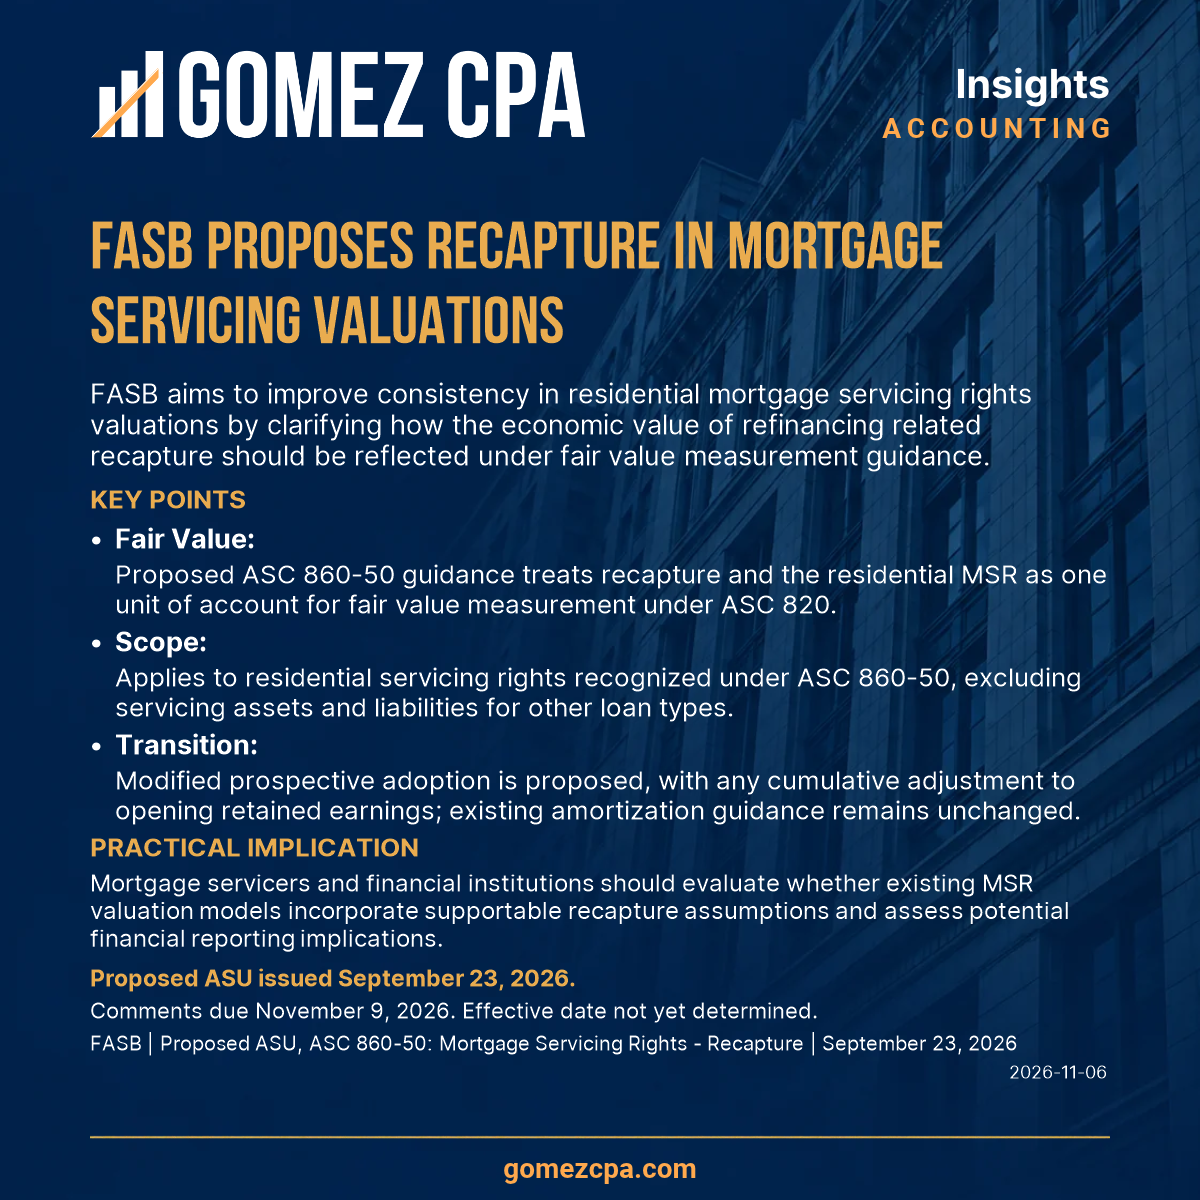
FASB has proposed amendments to ASC 860-50 that would require mortgage servicers to consider the economic value of recapture when measuring residential mortgage servicing rights (MSRs) at fair value under ASC 820.
What is recapture, and why does it matter?
When a borrower refinances a mortgage, the original loan is paid off and the associated servicing right generally terminates. However, the existing servicer may retain the borrower relationship and obtain servicing rights on the new mortgage. That potential future servicing business has economic value, even before refinancing occurs.
Currently, some mortgage servicers incorporate this recapture potential into MSR fair value measurements, while others exclude it. FASB's proposal would address this inconsistency by treating recapture and the existing residential MSR as a single unit of account for fair value measurement.
For controllers and financial reporting teams, the implications extend beyond the valuation model itself. Recapture assumptions must reflect market-participant expectations, including refinancing activity, customer retention probabilities, and the anticipated net economic benefits of future servicing relationships.
The distinction between subsequent measurement methods is also important. Entities using the fair value method would incorporate recapture into ongoing valuations. Those using the amortization method would consider recapture in fair value measurements for impairment testing, while existing amortization requirements would remain unchanged.
The proposal could affect reported MSR valuations, earnings, impairment assessments, and related valuation controls, depending on an institution's current methodology.
Status: Proposed ASU issued September 23, 2026. Comments are due November 9, 2026. No effective date has been established.
Source: FASB | Proposed ASU, Transfers and Servicing (ASC 860-50): Mortgage Servicing Rights - Recapture
Disclaimer: This brief is provided by GOMEZ CPA for general informational and educational purposes only. It is not intended and should not be construed as tax, accounting, legal, investment, or financial advice.
© 2026 Gomez CPA. All rights reserved.