IRS Expands Retirement Plan Self Correction
Published Oct 28, 2026 · Insights Brief
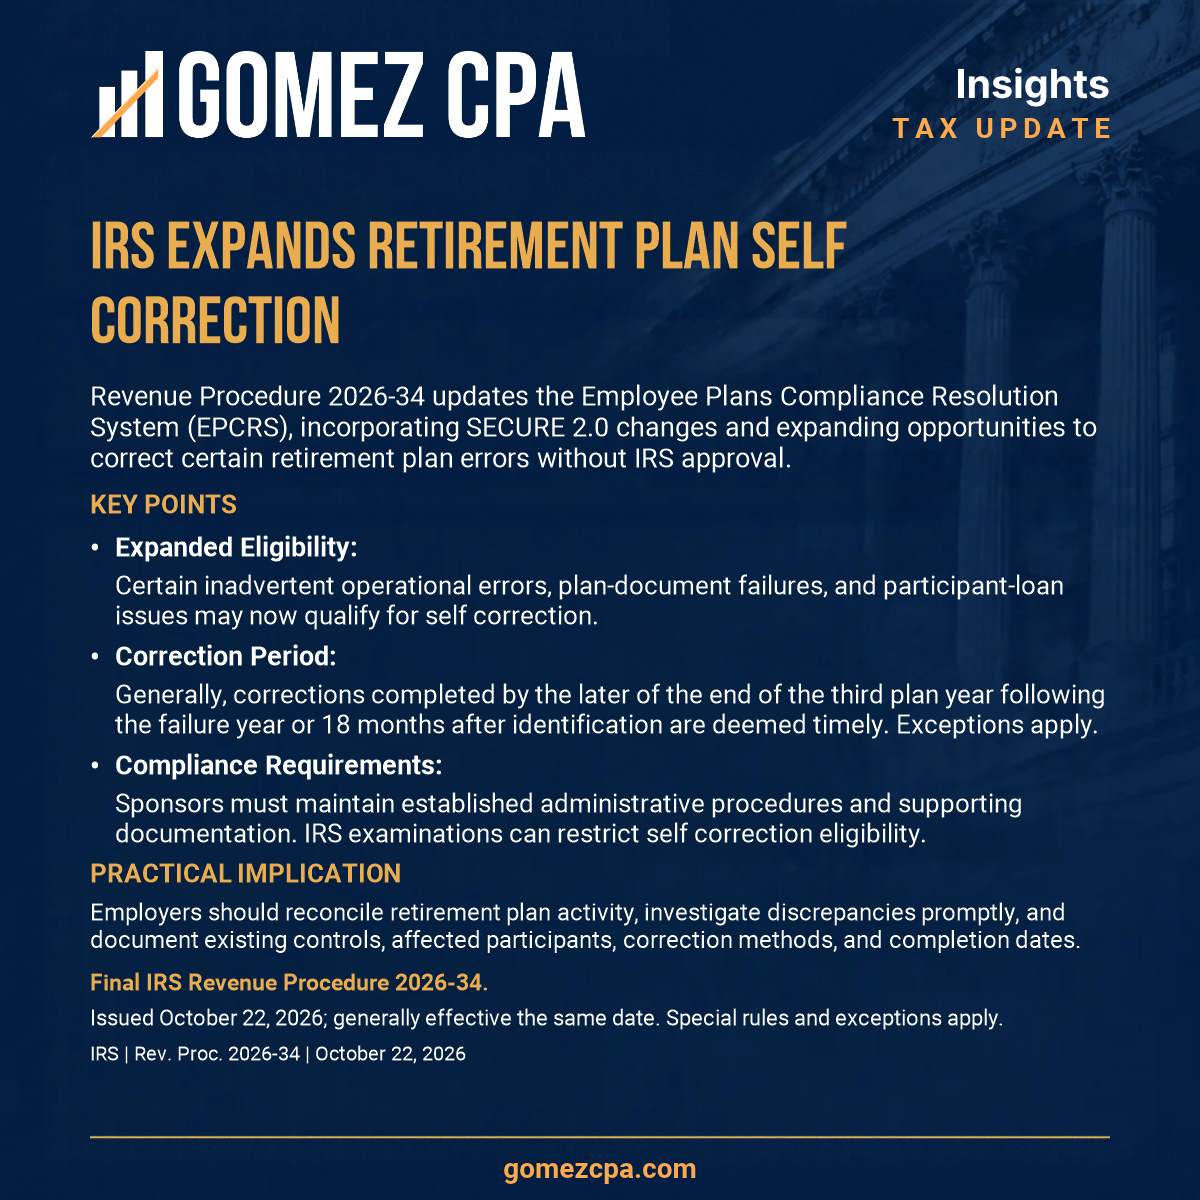
IRS expands retirement plan self correction opportunities, but compliance controls remain essential.
IRS Revenue Procedure 2026-34 updates the Employee Plans Compliance Resolution System (EPCRS), incorporating SECURE 2.0 provisions that broaden the types of retirement plan errors employers may correct without prior IRS approval.
The updated guidance also clarifies correction periods and reinforces the importance of established, routinely followed compliance procedures.
One important distinction, an IRS examination does not automatically eliminate eligibility for self correction.
However, the circumstances under which employers can continue correcting failures become more restrictive.
For plan sponsors, the key takeaway is to identify errors early, maintain evidence of compliance procedures, and document corrective actions. Effective October 22, 2026. Source: IRS Revenue Procedure 2026-34
Revenue Procedure 2026-34 (official PDF) #GomezCPA
Disclaimer: This brief is provided by GOMEZ CPA for general informational and educational purposes only. It is not intended and should not be construed as tax, accounting, legal, investment, or financial advice.
© 2026 Gomez CPA. All rights reserved.